
Sunday, September 27, 2026

Saudi Arabia locks in $15B AI infrastructure deals in 30 days, challenging US-China dominance

Saudi Arabia secured over $15 billion in AI infrastructure commitments from AWS, Google Cloud, AMD, and Nvidia within 30 days, positioning the Kingdom as the world's third-largest AI infrastructure spender after the US and China. The concentrated investment pattern signals coordinated government strategy as the Kingdom pivots The Line megaproject from urban development to a regional AI data-center hub.

Saudi Arabia locks in $15B AI infrastructure deals in 30 days, challenging US-China dominance
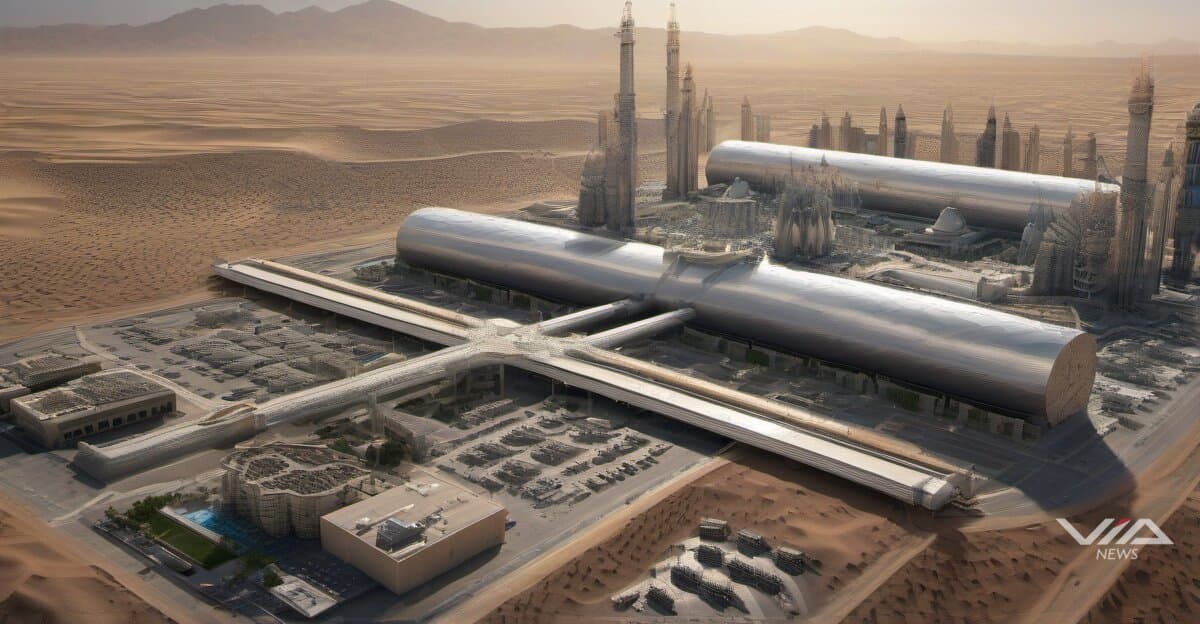
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Saudi Arabia secured over $15 billion in AI infrastructure commitments from AWS, Google Cloud, AMD, and Nvidia within a 30-day window, establishing itself as the world's third-largest AI infrastructure spender behind only the US and China for 2026.

AWS committed $5.3 billion to expand cloud infrastructure in the Kingdom. Google Cloud announced a new Saudi region with AI-optimized data centers. AMD signed agreements for chip design operations and AI accelerator supply. Nvidia partnered on sovereign AI infrastructure including DGX systems and training facilities.

The concentrated 30-day timeline indicates coordinated governmental strategy rather than independent corporate decisions. Saudi Arabia's Public Investment Fund is co-investing alongside the technology companies across multiple projects.

The Line megaproject is undergoing a strategic pivot from its original 170-kilometer linear city concept to function as a regional AI data-center hub, prioritizing compute infrastructure over residential and commercial development.

Middle East AI compute capacity is projected to grow 340% by 2027, with Saudi Arabia accounting for 60% of regional expansion. The Kingdom's positioning breaks the US-China duopoly on AI infrastructure, offering nation-states without domestic chip manufacturing a third option for AI sovereignty initiatives.

The Kingdom's $40 billion total AI investment target through 2030 exceeds the combined AI budgets of all other Middle Eastern nations. Enterprise AI adoption across the MENA region is expected to accelerate within 6-12 months as infrastructure comes online, driven by local language model development, government AI services, and regional data residency requirements.

Industry analysts assign 85% confidence to the Middle East emerging as a third major AI infrastructure hub by 2027. Saudi commitments represent multi-year purchase agreements that could redirect chip inventory from global enterprise customers to government projects, potentially reshaping the AI supply chain.

In this story · Knowledge Files

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Vertical AI Agents Attract a Funding Wave Across Fintech-Adjacent Industries
A cluster of AI-native startups applying autonomous agents to narrow, operational problems — hotel front-desk staffing (Dextr AI), identity/fraud risk for financial institutions (Baselayer), insurance distribution (Napo, Connie Health, MGT Insurance) — closed seed-to-Series A rounds within days of each other in September 2026, with CB Insights running a coordinated CEO interview series to spotlight them. The pattern points to agentic AI maturing from generic chat tools into vertical, revenue-generating products, with identity verification for AI agents themselves (Baselayer) emerging as a new fintech infrastructure category responding directly to AI-driven fraud risk.
Our read on the data ›
Signals we're tracking
Satellite-Terrestrial Network Integration Acceleration
Increased investment and launches in hybrid satellite-cellular networks across telecom industry; competitive responses from other carriers; regulatory activity around satellite spectrum; expansion of emergency/rural connectivity use cases
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,984
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,984 facts checked against source5,306 source documents archived
Query this data → isubstrate.com