
The success of the internet age is riding on the back of many breakthroughs. Besides advanced computer hardware, the software part is critical to the ultimate functioning of the technology industry. Admittedly, software publishers make up the backbone of the technology industry, especially the computing sector.
According to a 2015 McKinsey report, the software industry is one of the fastest-growing and fast-changing in the world. Indeed, both software developers and publishers are at the center of the culture of technological disruption. The fast-changing nature of the industry implies that companies have to focus more on their main priorities. As such, software publishers and software developers alike are increasingly spending effort and resources on efficiency and rapid profitability.
As of late 2017, the software publishers industry was worth $474.5 billion. At the time, the Asia Pacific region made up the largest share of the industry. Indeed, the region accounted for more than 39.50% of the market share. Interestingly, the changing dynamics in the industry are behind the pace of mergers and acquisitions, which is just picking up. Notably, IBM Corporation, SAP, Microsoft, and HP Inc. remain the most significant players in the industry on a global scale.
Where is the software publishers industry more active?
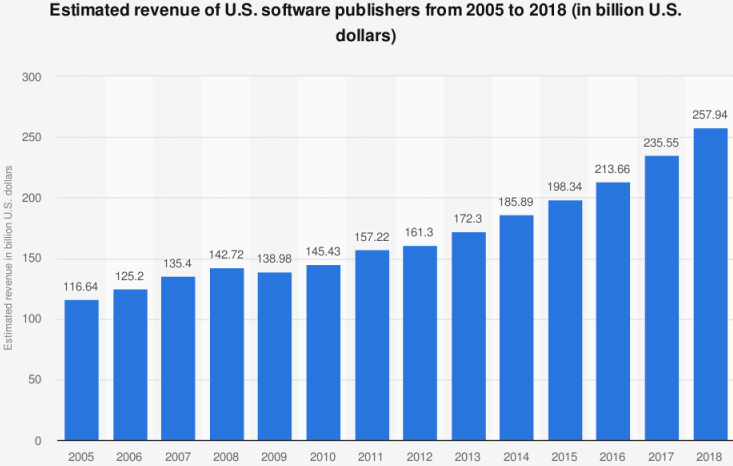
In terms of countries, the US takes up the largest share of the industry. It is because most of the largest companies in the industry are American. As of July 2019, the software publishers in the US earned revenues of approximately $270 billion. It is after the industry experiencing an average annual growth of 5% from 2014 to 2019. Interestingly, the last three years to 2019 has seen the US software publishers industry expand at an annual rate of 9.1%. The US software publishers' revenue growth has never failed to increase since 2009, according to figures by Statista.
The United Kingdom is another country that has a vibrant software publishers industry. As of 2019, software publishers in the UK earned £2 billion ($2.61 billion) in revenues, according to IBISWorld. The revenue was a result of the activities of around 2,322 companies. Notably, the UK software publishers industry is growing faster than that of the US. In the five years to 2019, the sector expanded by 7.7% and is forecast to increase the pace in the years ahead.
Interestingly, more than half of the software publishing companies in the UK are ten years or older. Further, the majority of these companies are micro-players, which is to say that their activities do not compare to conglomerates like IBM Corp. 92% of the software publishers in the UK are micro-enterprises. Just about 0.3% of the software publishing enterprises are significant.
Sectors where software publishing enterprises are more active
The largest software publishers develop system software (operating systems). Notably, the system software is responsible for running computers and many other electronic devices. Additionally, the system software sector takes up the most significant share of the software industry. Microsoft is the most significant system software company globally. The company registers more than $97.58 billion in annual sales. Besides system software, Microsoft produces personal computers and other electronics. Other major players in the system software sector include Oracle, SAP, Symantec, and VMWare.
Besides the system software sector, the software publishing industry includes application software publishing sector, custom application design and development, software adaptation, embedded software, and desktop applications and others. Of the companies mentioned above, like Microsoft, the majority of them operate in the majority of the sectors.
The short-term and long-term outlook
Usage of computers and other electronics is increasing as technology adoption continues to penetrate worldwide. As such, this is evidence that the software publishers industry has an opportunity to grow. Specifically, the maturing of artificial intelligence and machine learning will increase the demand for system software. Besides, the rise of new technology like blockchain is excellent in terms of driving up demand for software. That is why companies like IBM and Microsoft are leading in research in the blockchain.